

Introduction
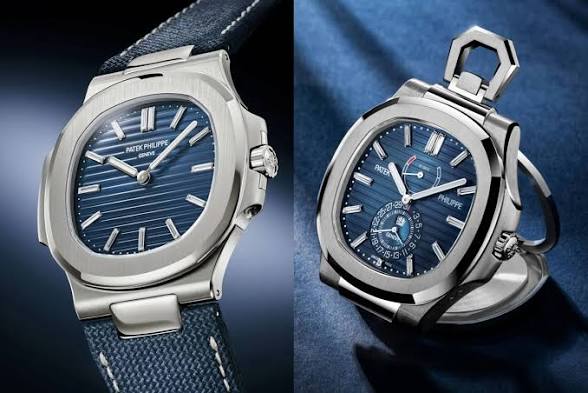
The seizure of a pre-owned Patek Philippe Aquanaut watch valued at ₹94 lakh at Indira Gandhi International Airport has brought attention to India’s customs rules on carrying expensive personal belongings while travelling internationally. The incident raises an important question: can passengers bring luxury watches into India without paying customs duty simply because the watches are used or intended for personal use?
The incident also highlights the importance of declaring dutiable goods and understanding the difference between personal effects and articles that require customs clearance.
What Happened at Delhi Airport?
According to reports, Delhi Customs officials intercepted an Indian passenger arriving from Dubai at Terminal 3 of Indira Gandhi International Airport on November 11, 2026. The passenger was travelling on a SpiceJet flight.
Acting on intelligence inputs, customs officers directed the passenger, who had entered through the Green Channel, for further screening. During the examination, a metal detector alert led to a personal search and inspection of his baggage. Officers recovered a pre-owned Patek Philippe Aquanaut wristwatch.
A chartered engineer examined the watch, confirmed its authenticity and assessed its value at ₹94 lakh. Customs officials seized the watch under Section 110 of the Customs Act, 1962, and arrested the passenger under Section 104 of the Act.
Delhi Customs announced the seizure on November 17, 2026, and stated that further investigation was underway. However, the authorities had not publicly clarified the passenger’s declaration status or the specific alleged violation at the time of reporting.
What Do the Baggage Rules, 2026 Say?
India’s Baggage Rules, 2026, which came into force on February 2, 2026, govern the duty-free clearance of goods carried by passengers arriving in India.
Under Rule 3, passengers are permitted to bring used personal effects required for their daily necessities and travel souvenirs, subject to the conditions prescribed under the Rules. The definition of personal effects considers articles that a passenger may reasonably require for personal use during the journey. Commercial goods are excluded.
However, the fact that an article is pre-owned does not automatically establish that it qualifies as an exempt personal effect. Customs authorities may examine the nature of the item, its intended use and the circumstances in which it is being carried.
Rule 5 also provides a general duty-free allowance for eligible passengers arriving in India by modes other than land. Indian residents, tourists of Indian origin and foreigners holding valid visas other than tourist visas are entitled to an allowance of up to ₹75,000. Foreign tourists of other nationalities are entitled to an allowance of up to ₹25,000, subject to the prescribed conditions.
New articles, including wristwatches, may qualify under the applicable general free allowance. However, goods exceeding the permitted allowance or otherwise requiring customs clearance cannot be treated as automatically duty-free.
When Must Passengers Declare Luxury Watches?
International passengers must understand the difference between the Green Channel and the Red Channel at customs checkpoints.
The Green Channel is meant for passengers who are not carrying dutiable or prohibited goods requiring declaration. The Red Channel is meant for passengers carrying goods that need to be declared for customs assessment.
A passenger carrying a valuable watch or another article that requires customs clearance must make the appropriate declaration and approach the Red Channel. Failure to declare dutiable goods may lead to detention or seizure and further legal proceedings under the Customs Act.
Passengers travelling with expensive watches, jewellery or electronic equipment that they already own may also consider obtaining an export certificate before leaving India. This can help establish that the article was taken out of the country earlier and is being brought back, subject to verification by customs authorities.
Can Customs Arrest a Passenger for Carrying an Undeclared Watch?
The Customs Act, 1962, provides powers to customs officers to seize goods and arrest individuals in specified circumstances.
Section 110 authorises the seizure of goods where the proper officer has reason to believe that the goods are liable to confiscation under the Act. Section 104 deals with the power to arrest a person where the statutory conditions are satisfied.
The Central Board of Indirect Taxes and Customs (CBIC) arrest guidelines identify certain cases involving unauthorised importation of goods in passenger baggage, with a market value of ₹50 lakh or more, as exceptional circumstances in which arrest may be considered.
However, the value of the goods alone does not automatically establish an offence or make arrest mandatory. Authorities must consider the nature of the alleged violation, the individual’s role, the available evidence and the circumstances of the case. Arrest must be exercised in accordance with the law and the applicable guidelines.
In the Delhi Airport incident, the watch was valued at ₹94 lakh, which is above the value threshold referred to in the arrest guidelines. Nevertheless, the specific allegations and the final outcome will depend on the investigation and applicable legal proceedings.
What Should International Travellers Keep in Mind?
The seizure highlights the importance of understanding customs requirements before travelling with expensive personal belongings. Passengers should check the applicable duty-free allowance, distinguish between used personal effects and newly acquired articles, and declare goods that require customs clearance.
They should also preserve purchase invoices, ownership records and relevant travel documents. Where valuable articles are taken out of India and brought back, obtaining an export certificate can help avoid disputes about their origin.
The case demonstrates that the description of an item as a personal belonging does not, by itself, settle its customs treatment. The applicable baggage rules, the nature of the article and the circumstances of its import remain relevant to determining whether customs duty or other legal consequences arise.